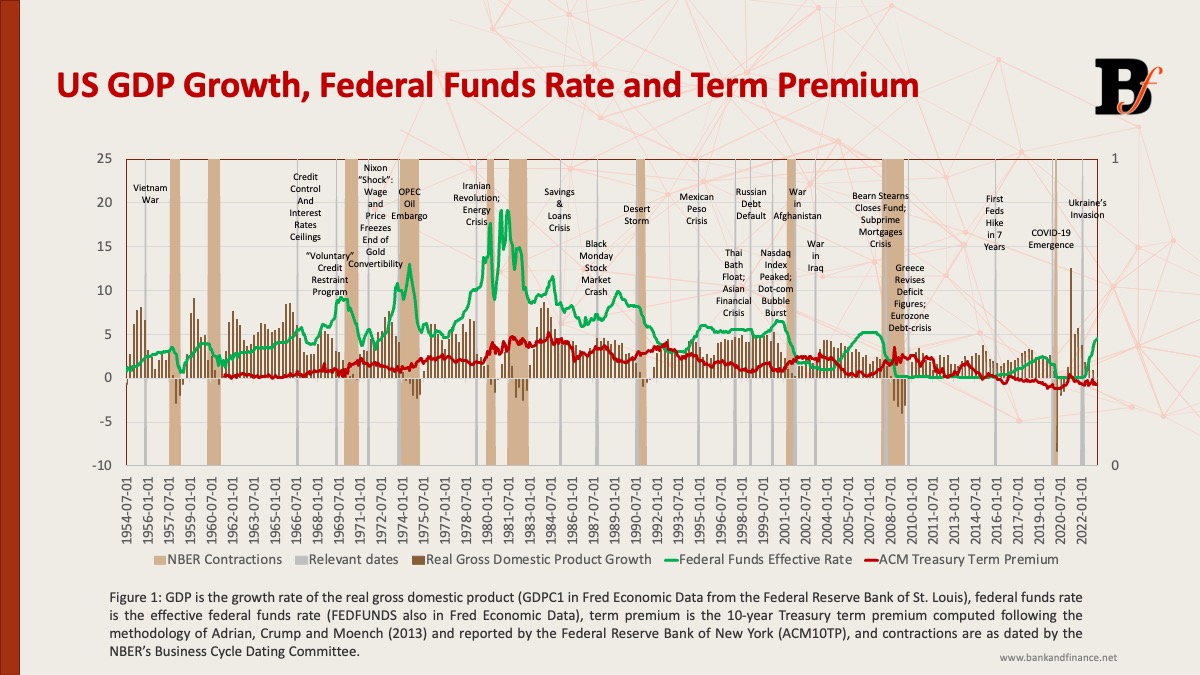
In this research project, we show the importance of considering non-linearities when analyzing financial conditions and the macroeconomic-financial linkages. Conclusions include: Based on a model fit criteria, the introduction of Markov switching in parameters and variances improves the fit of a macroeconomic VAR model with financial variables, with the best fit in an unrestricted modelContinue reading “Financial conditions and monetary policy: the importance of non-linear effects”
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

